The right time to buy or sell in Parkland depends on more than a citywide price headline. Comparing similar homes, watching how inventory changes, and planning for the costs of a move can give you a clearer picture of your options. Here’s how to read the signals before making your next decision.
Start With the Homes You Would Actually Consider
A market report can tell you whether Parkland’s median sale price has moved, but it cannot tell you what every home is worth. The median is the midpoint of the homes that sold during a particular period. If more large or recently updated properties close in one month, the median may rise even when comparable homes have not changed much in value.
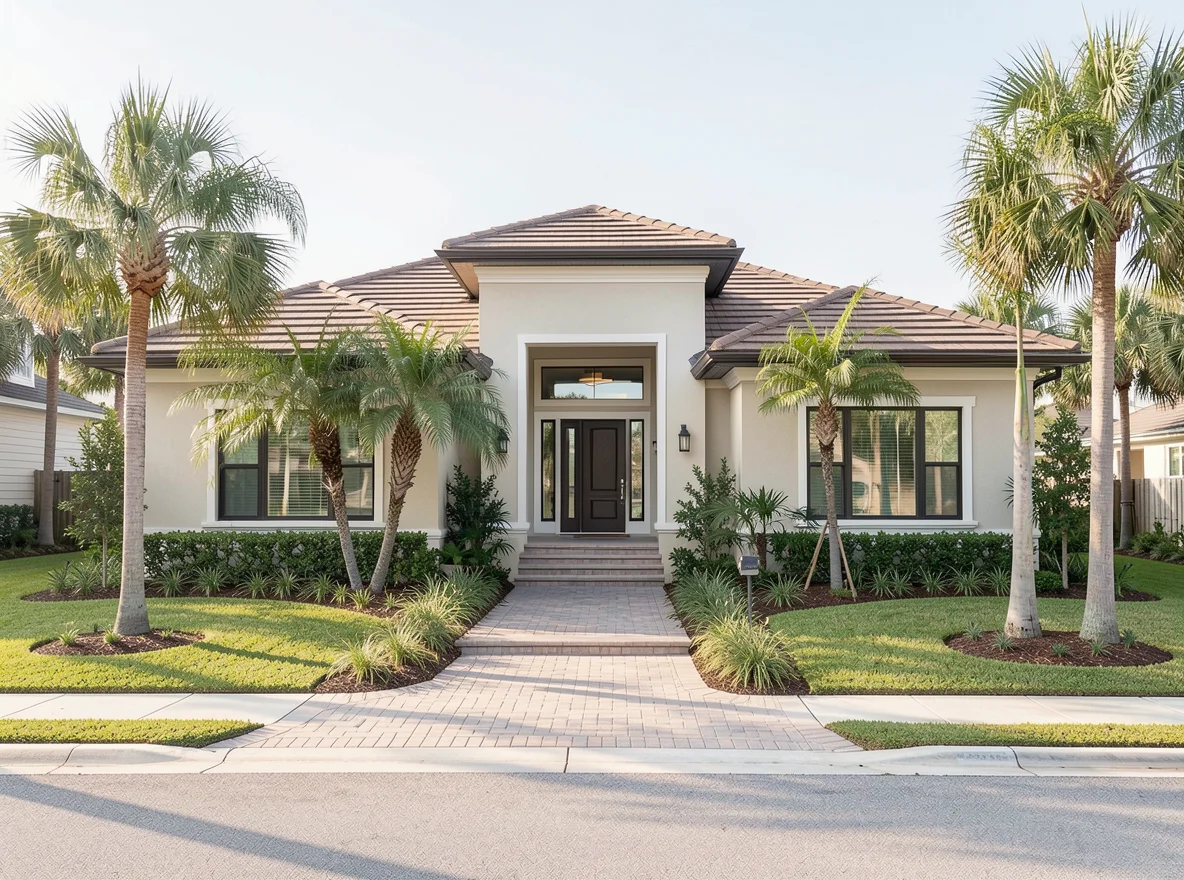
For a more useful comparison, look at recent sales of properties with similar square footage, lot size, condition, and amenities. A renovated kitchen, a pool, or a waterfront setting can affect how buyers evaluate a home. Community fees and restrictions may also influence the overall cost and appeal, so compare those details rather than relying on price per square foot alone.
Active listings show what sellers are asking; closed sales show what buyers agreed to pay, though a contract may have been negotiated weeks earlier. Pending listings can offer a sense of current activity, but their final prices may not be public until closing. Viewing all three together helps put an individual asking price in context.
A change in Parkland’s median price may reflect a different mix of homes sold—not a matching change in the value of your particular property.
For both buyers and sellers, the most relevant comparison is often a smaller group of homes competing in the same price range. Ask for the dates behind the numbers, too: conditions can shift between the time a contract is signed and the time it closes.
What Inventory Can Tell You
Inventory is the number of homes available for sale at a given time. More choices can give buyers room to compare properties and terms; fewer comparable listings can make each suitable opportunity more consequential. Neither situation guarantees a particular outcome for an individual home.
Watch how many properties are newly listed, how many go under contract, and how long comparable homes remain on the market. A growing list of active homes alongside slower sales may indicate that buyers have more options. If suitable listings are being absorbed quickly and few replacements are appearing, preparation and prompt decisions may matter more.
Also look beyond the total count. A buyer searching for a particular layout or outdoor feature may see a very different market from someone considering a broader range of properties. For a seller, the competing inventory that matters most is the group a buyer is likely to tour alongside your home.
Days on market deserves context. A longer listing period can reflect ambitious pricing, condition, limited showing availability, or a property’s distinctive features. It can also create an opening for a conversation about price or terms, but it does not automatically mean a seller must accept a discount.
Timing a Purchase Without Guessing the Peak
Waiting for a perfect market can be difficult when prices, inventory, and financing costs do not move in lockstep. Instead, begin with the monthly payment and cash requirements that feel manageable, then compare those figures with the homes currently available. A lender can explain how a rate change or a different down payment would affect your budget.
Include more than principal and interest in the calculation. Property taxes, homeowners insurance, potential flood insurance, association dues, maintenance, and closing costs can change the picture. Ask your lender and insurance professionals for estimates based on the property you are considering; a seller’s existing tax bill or insurance premium may not reflect your future costs.
When a home meets your needs, compare its asking price with recent sales and the current competition. Your offer can address more than price: financing, inspection periods, closing date, and other terms all matter. Make decisions about contingencies with an understanding of the risks rather than assuming that the strongest offer is simply the highest one.
A lower purchase price does not always mean a lower monthly cost. Compare financing, taxes, insurance, and association dues before deciding what fits your budget.
If the available homes do not meet your priorities, use the time to refine your search and financing plan. Having a clear list of must-haves, preferred features, and acceptable trade-offs makes it easier to respond when a suitable property appears.
A Seller’s Plan for a Changing Market
Pricing is a launch decision, not just a number on a listing. Begin with recent comparable sales, then consider active competition, property condition, and any meaningful differences between those homes and yours. A proposed price should have a rationale that connects to the choices buyers can see today.
Preparation can make those comparisons work in your favor. Address practical repairs, consider whether targeted updates are worthwhile, and make sure the property is ready to photograph and show. Gather information about major systems, renovations, permits, and any association requirements so buyers can evaluate the home with fewer unanswered questions.
Once the listing is active, review feedback and activity with your agent. Showing requests, competing listings, and offers provide information, although a quiet first week alone may not tell the whole story. Agree in advance on when to reassess the strategy and what evidence would justify a change in price, presentation, or terms.
Choose a Timeline That Works for Your Move
The market is only one part of the decision. A move may also depend on a purchase deadline, the sale of another property, access to financing, or the time needed to prepare a home. Map out those practical steps before choosing a target date, and leave room for inspections, appraisal, underwriting, and closing.
If you are both buying and selling, discuss how each transaction will be funded and what happens if the schedules do not align. Options may include negotiating a longer closing or temporary occupancy, but availability and suitability depend on the parties and the contract. Your lender, agent, and legal advisers can help you understand the trade-offs.
Parkland buyers and sellers do not need to predict every turn in the market to make a thoughtful move. Start with current, property-specific information, revisit it as listings and sales change, and make a plan grounded in your finances and priorities. Coryn Mock can help you compare the local options and decide what your next step should be.